Picking your first travel credit card? Here’s how to choose the right starter card and turn spending into trips.
Disclosure: We’re not financial advisors, and this isn’t financial advice. Pay your balance in full each month, and only apply for cards you can handle. This post may contain affiliate links, which earn us a commission at no cost to you. Please read full disclosure for more information.
Opening your first travel card feels overwhelming. We’ve been to over 70 countries, many of them using points, and here’s how we’d think about starting.
One thing first: sign-up bonuses are often one-time offers.
Your first card matters, because the order you open cards in can change which bonuses you’re eligible for later.
Before diving in, remember: If you can’t use credit responsibly, it’s better not to start at all. The last thing you want is to go into debt trying to save on travel.
Step 1: Pick a Goal
Do you have a destination? A dream trip? Mostly domestic or international?
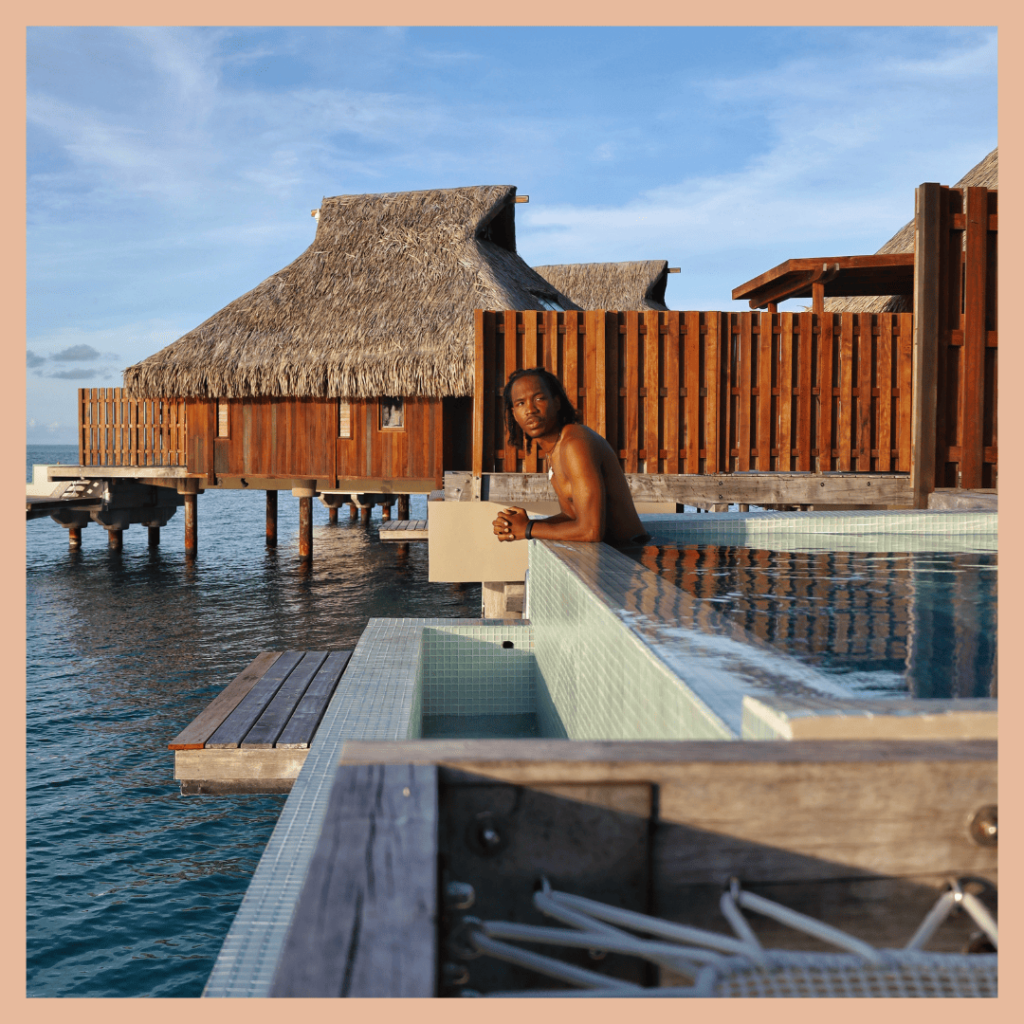
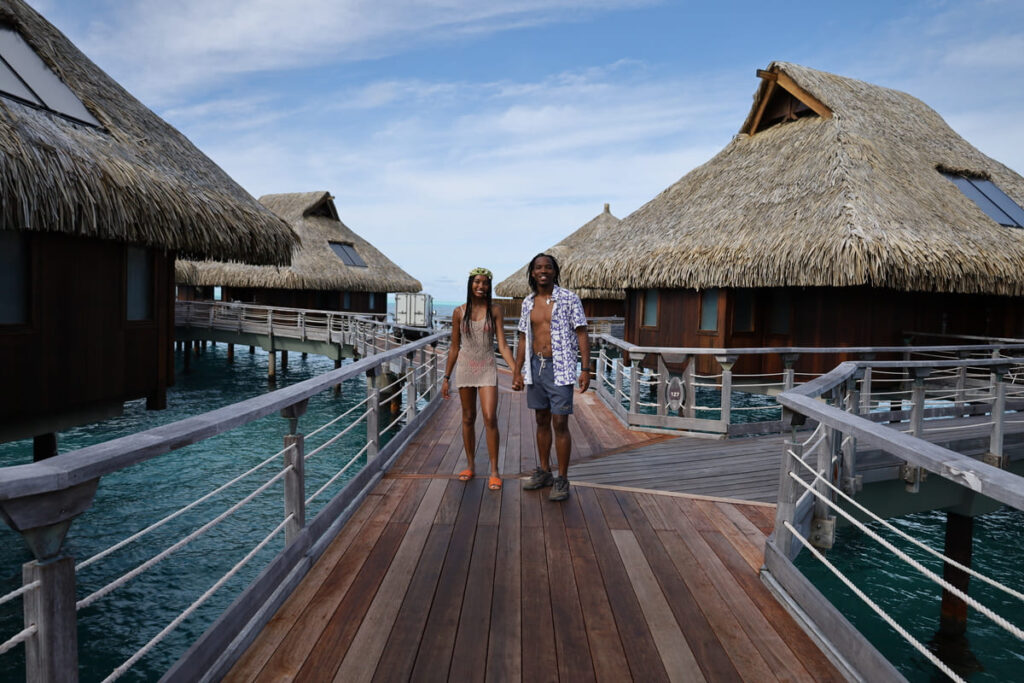
Our goal was an overwater bungalow in Bora Bora.
We used a flexible Chase card for flights (flying United via Tahiti) and a Hilton card for the hotel, and paid for four nights in a private bungalow with points.
No specific goal yet? Pick a flexible card. Transferable points keep your options open.
How we’d do it: before we book anything with points, we check what each point is worth. We walk through that with real screenshots in Part 6 of our guide, Travel the World with Points.
Step 2: Check Your Credit
Most travel cards want good to excellent credit.
Check your score with a free tool like Credit Karma, use the issuer’s pre-approval tool if there is one (no hard pull), and remember that applying creates a hard inquiry.
If your credit needs work, build it first.
Step 3: Match the Card to How You Live
Perks like lounge access are only worth a fee if you’d use them.
Look at where you already spend (dining, groceries, travel) and avoid high fees until the perks clearly pay for themselves.
Step 4: Plan the Sign-up Bonus
Bonuses come with a minimum spend.
Plan regular expenses to reach it without overspending.
If you can’t reach it comfortably, skip the bonus and pick a card you can use well.
Bonus amounts change often, so check the issuer’s page for the current offer.
Four Beginner-friendly Cards
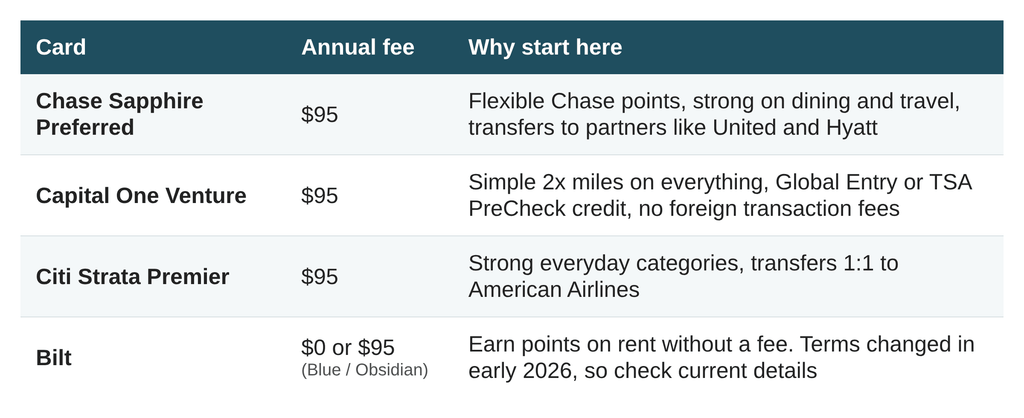
Two tips: if you want a Chase card, apply for it first. Chase’s 5/24 rule usually denies you if you’ve opened five or more personal cards in the last 24 months.
And pay your balance in full every month, or interest will wipe out your rewards.
When a hotel card makes sense: if you already know you’ll stay at one chain, a co-branded card like Hilton Honors can be great. If you don’t, a flexible card is safer.
How to Choose
- Have a specific goal? Pick the card that fits it.
- No goal yet? Pick a flexible card.
- Travel abroad? Make sure there’s no foreign transaction fee.
- Not sure a fee is worth it? Compare the perks you’d use against it.
Final Thoughts
The best card is the one that fits your life.
Transfer partners are the most powerful tool we use, which is why we wrote a $7 guide on them.
Where to go from here Just picking a card? Our free guide, Which Travel Credit Card Should You Get?, will narrow it down in a few minutes. Want the whole path in one place, from choosing your first card to booking the trip? That’s what we put in Travel the World with Points, our beginner’s guide to cards, points and your dream trip.